A recent journey along China’s remarkable G65 Baomao Expressway left me thinking about more than tunnels and highways. Behind such engineering achievements lie decades of investment in knowledge, research and skilled people.
Malaysia has its own impressive accomplishments, from tunnelling innovation to advanced manufacturing. But are we doing enough to develop technologies of our own? And what can we learn from countries that have made the transition from buying technology to creating it?
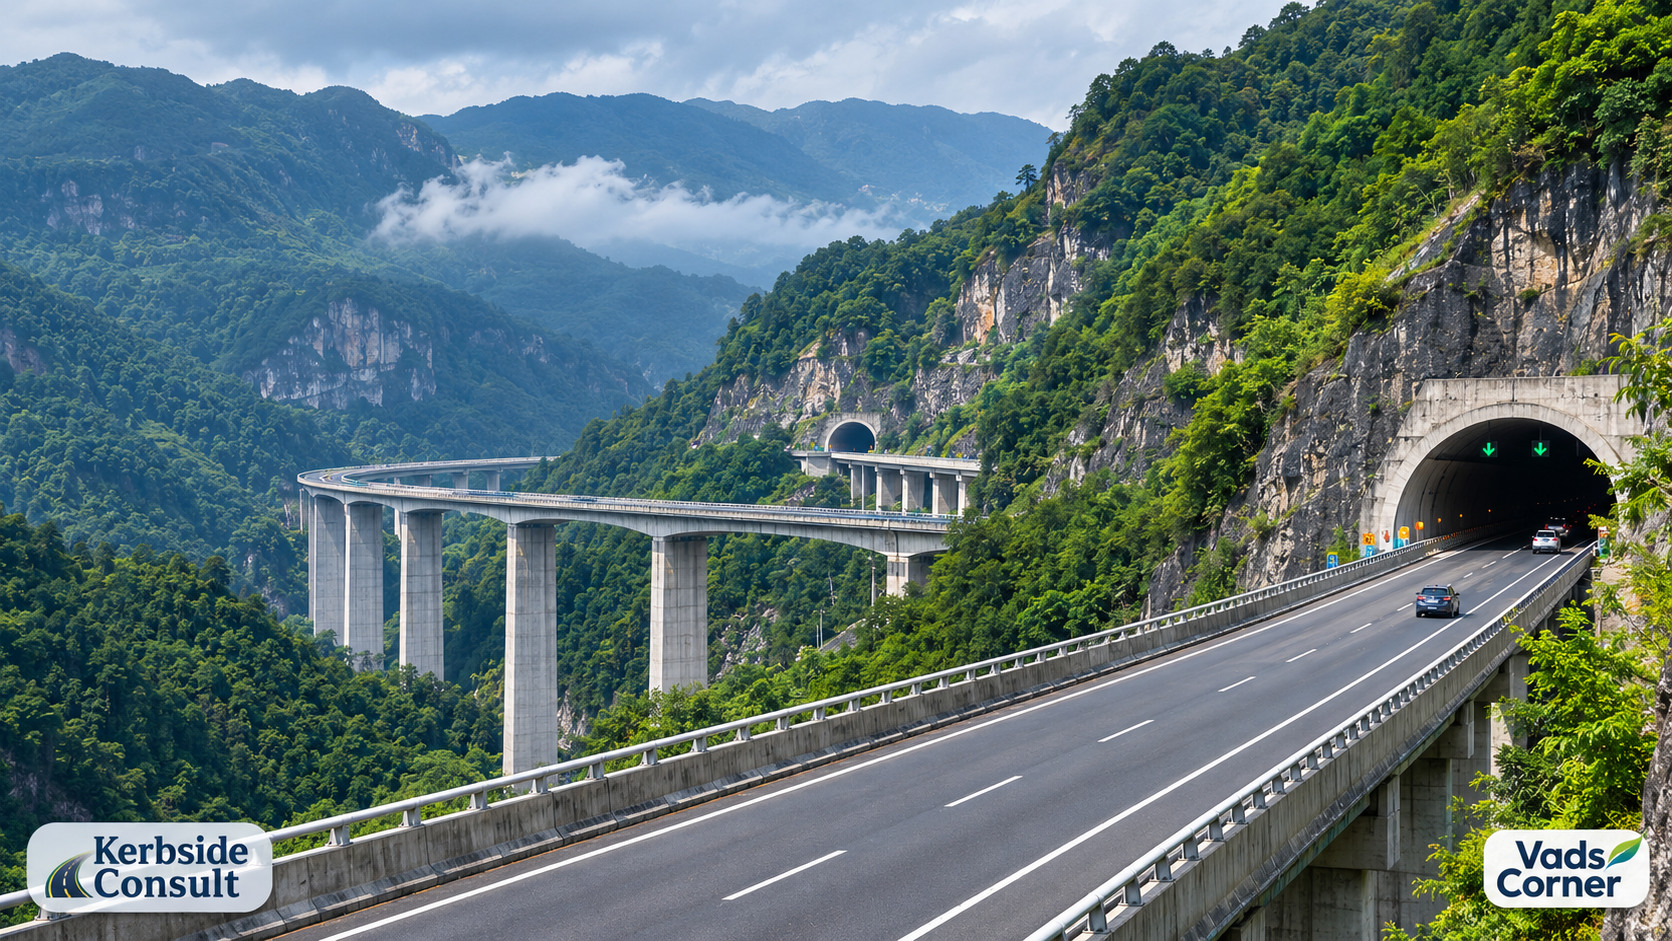 AI-generated illustration
Contents
- A journey through the mountains
- From buying machines to building them
- Malaysia's tunnelling achievements
- MRT, railways and highways
- Other industrial successes
- Why not more R&D?
- The automotive question
- What about healthcare?
- What should Malaysia aim for?
- Back to the mountains
- At the kerbside
- Sources & further reading
A journey through the mountains
During my recent visit to China, we travelled from Chongqing to Wulong Karst along the G65 Baomao Expressway, via Nanchuan. I later learned that the G65 is no ordinary highway: it stretches roughly 3,000 kilometres from Baotou in Inner Mongolia to Maoming in southern China. In Chongqing it runs from Jieshi in Banan District through Nanchuan to Wulong, the stretch we travelled; the Jieshi–Nanchuan section opened in 2007 and the Nanchuan–Wulong section in 2009.[1]
What struck me most was the succession of tunnels through the mountains. We would emerge briefly into daylight, cross a bridge or travel along a mountainside, and then disappear into another tunnel. I estimated that we must have travelled through nearly 40 kilometres of tunnels.
Later, I came across engineering documentation for the approximately 135-kilometre Jieshi–Wulong expressway section, listing 14 tunnels with a combined length of approximately 39.83 kilometres. The longest, Baiyun Tunnel, measures approximately 7.2 kilometres. These are figures for the documented expressway section, not a measurement of the distance our vehicle travelled inside tunnels. (The operator's own summary page gives slightly different subtotals, about 36.6 km; I have used the detailed tunnel table in the engineering drawings, whose entries add up to 39.83 km.) My impression was not far off.[2]
There is now a second route through these mountains. A new parallel Chongqing–Hunan expressway, fully open since December 2025, meets the G65 at the Shuijiang North interchange, and about 80 percent of its 280 kilometres runs on bridges or through tunnels.[3], [4], [5] We did not travel it.
It was not simply the number or length of the tunnels that impressed me. I wondered about the planning, engineering knowledge, machinery and skilled workforce required to build such a transport network. It brought to mind China's transformation from dependence on imported advanced tunnelling machinery to becoming a major manufacturer of its own.
The tunnels were only one example of how far, and how fast, China has moved. Wherever we went, the same thing struck me. Cities crowded with skyscrapers. Roads and railways that simply worked. And a system that let us, as foreign visitors, use our passports as our tickets once we had bought them, whether for the train or for a park. No paper ticket was needed at all.
None of that happens by accident. Behind the convenience lie planning, technology and systems that talk to each other, built over years.
And that led me to another question. What about Malaysia? We have been industrialising for decades, attracting international manufacturers and developing considerable technical expertise. Yet how much of the technology behind our industries do we actually develop and own?
From buying machines to building them
China's tunnelling industry offers a useful lesson. In the 1990s and early 2000s, it relied heavily on imported advanced tunnelling machinery, particularly from established German and Japanese manufacturers. A Japanese maker's 2001 announcement of a shield machine order for Tianjin's metro, for instance, noted that stable, long-term demand was expected as several Chinese cities built subways.[6] Buying the machines was one thing. Learning to design and build them was far harder.
China invested in engineering research, technical training and domestic manufacturing. In 2008, China Railway developed China Railway No. 1, a modern earth-pressure-balance shield machine with domestically developed intellectual property. It began work on a metro project in Tianjin on 6 February 2009. This was not China's first tunnelling research, but an important milestone in modern shield-machine development.[7], [8] One of its makers later described the effort as six years of independent research.[9]
Two things stand out. First, there was a very large and steady home market: dozens of cities building metros gave domestic makers somewhere to test, fail and improve. Second, the effort was sustained for years rather than a single project or budget cycle. Both are easier to say than to copy.
There is also an irony that Malaysian readers may enjoy. China's first exported domestically produced TBM followed a China Railway win on a Kuala Lumpur metro project,[8] and two TBMs built by China Railway Engineering Equipment Group (CR-50 and CR-51) each bored a 2,814-metre tunnel for the Klang Valley MRT, breaking through in October 2014.[10] Our MRT was, in effect, an early customer for China's shield-machine industry.
We should distinguish these machines from the construction methods used for mountain highway tunnels. Many road tunnels are excavated by drilling, blasting and other techniques rather than large urban-rail TBMs. Both, however, depend on accumulated engineering expertise, specialised suppliers and long-term investment.
Malaysia's tunnelling achievements
It would be unfair to say Malaysia has only bought its technology. In tunnelling, we have done more than that.
Consider Kuala Lumpur's SMART Tunnel, opened in 2007. Combining stormwater management with a road tunnel, it addressed two difficult urban problems: flooding and traffic congestion. Its design and construction required considerable engineering ingenuity.[11]
The Klang Valley MRT went further. Kuala Lumpur's unpredictable limestone formations and underground cavities make tunnelling particularly challenging. Malaysian engineers from MMC-Gamuda worked with Germany's Herrenknecht to develop the world's first Variable Density Tunnel Boring Machine, launched in 2013. It was designed to handle difficult karstic ground conditions. This was genuine international technological collaboration, not simply the purchase of an off-the-shelf machine.[12]
Gamuda subsequently developed AI-based control software for autonomous TBM operation, first used on the Sydney Metro West tunnelling package, where two Herrenknecht-built machines are steered, operated and monitored by Gamuda's software.[13], [14] Note the distinction: the machines came from a German partner, while the intelligence that runs them is Malaysian. Gamuda also runs specialist tunnelling training.[13]
We do not manufacture complete TBMs on the scale of the world's largest producers. But Malaysian engineers have shown they can help create original technology. The harder question is how to repeat it.
MRT, railways and highways
Malaysia has substantial experience constructing MRT and LRT systems, electrified double-track railway lines, highways, bridges and complex urban infrastructure. Malaysian engineering companies have also delivered major projects overseas.
Our rail industry has acquired expertise in train assembly, maintenance, repair and systems integration. Yet much of the advanced rolling stock, propulsion, signalling and train-control technology still comes from overseas manufacturers.
There is a difference between constructing a railway, assembling a train and developing the technology that makes the train operate. All require expertise, but they are not the same level of technological ownership. Similarly, our highway construction achievements do not mean that every piece of specialised equipment or control system is locally designed.
Recognising that distinction is not a criticism of Malaysian engineers. It helps us identify where to invest next.
Other industrial successes
Medical gloves
Malaysia became one of the world's leading producers of medical gloves. Companies such as Top Glove, Hartalega and Kossan developed sophisticated manufacturing operations, automation and quality control. The industry's global market share was put at approximately 45% in 2024, ahead of China at about 28%.[15], [16]
That lead has not proved permanent. Analysts at TA Research estimate that Chinese makers raised their share from about 11% in 2019 to around 34% in 2025, while Malaysia's fell from about 63% to roughly 35%.[17] Other analysts, writing in August 2026, remain unconvinced that tariffs on Chinese gloves will bring a recovery.[18] Estimates differ by source and method, so treat the figures as indicative. The lesson for this article is plain. Knowing how to make something efficiently can be copied. Staying ahead takes continuing innovation.
Semiconductors
Malaysia has participated in the global semiconductor industry for more than five decades. Penang and other centres have developed considerable expertise in assembly, testing and packaging. Bank Negara Malaysia and MIDA both put Malaysia's share of global assembly, testing and packaging activity at about 13%, an official estimate for which neither gives a base year.[19] These are technically demanding operations, but there remains room to capture more value through original chip design, advanced engineering and intellectual property.
Policy is now pointing that way. The National Semiconductor Strategy of May 2024 set out RM25 billion in fiscal support, training for 60,000 engineers and at least 10 local design and advanced-packaging firms with revenues of RM1–4.7 billion.[20] In March 2025 Malaysia signed a national partnership with Arm to train 10,000 IC design engineers and give selected Malaysian companies access to Arm's technology,[21] reportedly paying US$250 million over 10 years for chip designs and IP.[22] Here is our theme again, in miniature: buying technology as a deliberate step towards building it. Licensing first has been a route many latecomers have used, but it only pays off if local firms go on to design products the world wants to buy.
Precision engineering
Homegrown companies such as ViTrox, Greatech, Pentamaster and UWC are described by MIDA as delivering automation platforms, automated optical inspection systems, precision engineering tools and cleanroom and handling systems for semiconductor fabrication and advanced packaging lines. These are firms making equipment, not simply operating imported machinery.[23]
We rightly celebrate foreign companies investing in Malaysian factories. We should also celebrate Malaysian companies that create technologies for the world market.
Why not more R&D?
Let us start with the number. Malaysia's R&D spending is modest. The latest national R&D survey (it is biennial) reports expenditure of RM18.16 billion in 2022, equivalent to 1.01% of GDP.[24], [25]
That was short of the national target. The National Science, Technology and Innovation Policy aimed for 2.5% of GDP by 2025 and 3.5% by 2030.[26] An Auditor-General report in early 2026 found that only one of the six 12th Malaysia Plan objectives had been met by June 2025; only experimental research expenditure met its target (60.97% against a 50% goal). The unmet objectives included GERD as a share of GDP, business expenditure on R&D, researchers per 10,000 of the labour force, a top-20 Global Innovation Index ranking and citizen patent applications; and only 34.1% of the projects audited were physically completed.[27]
How does that compare internationally? In 2024, South Korea devoted approximately 5.1% of GDP to R&D, Japan 3.6%, the United States 3.4%, Germany 3.1% and China 2.7%. These figures are from a later year than Malaysia's and should be read as a broad benchmark rather than a same-year ranking.[28]
Illustrative comparison; reporting years differ.
Major economies: 2024; Malaysia: 2022; Singapore and Thailand: 2023. Sources: [24], [28], [29], [30].
Within ASEAN, Malaysia compares more favourably. Singapore invests more, while Thailand's reported level is relatively close. Vietnam, Indonesia and the Philippines have reported lower levels in the available international series, although some observations are older.[29] Malaysia is not among the region's weakest performers. The larger gap is with economies that have built research-intensive industries.
There is also encouraging news. In the 2022 survey, industry's share of national R&D spending rose to about 51%, from 34% in 2020.[25] Business is moving in the right direction. The question is whether that spending is producing technologies that Malaysian firms own and sell.
Why does this gap persist?
Part of the explanation, I suspect, lies in our industrial structure. We have attracted multinational manufacturers, but some of their original research and product design remain overseas. Smaller Malaysian businesses may lack the capital and specialist staff for projects that take years to produce returns. Buying proven technology is often safer than developing something new.
Universities face another challenge. A promising discovery does not automatically become a product. It needs further development, testing, investment, manufacturing and customers. Academic incentives and commercial needs do not always align. Research also requires continuity: programmes cannot mature if priorities and support repeatedly change.
More government spending alone is not the answer. Businesses must keep investing in developing their own technologies, and universities need stronger industry partnerships. We should measure not only how much is spent, but how many useful technologies emerge, reach the market and compete internationally.
The automotive question
PROTON and Perodua helped develop local manufacturing, component suppliers, engineering expertise and skilled employment. These achievements deserve recognition. Yet international exports have been modest compared with major Japanese, Korean and Chinese manufacturers. A 2024 MITI statement, based on information from the two manufacturers, reported that they exported 24,272 vehicles from 2019 to September 2024.[31] Of these, 17,118 were PROTON and 7,154 Perodua.[32] Over roughly five and three-quarter years, that averages about 4,200 vehicles a year (my arithmetic).
The reasons are complex, including market size, policy, partnerships and commercial strategy. Partnerships deserve a word. In 2017 China's Geely took a 49.9% stake in PROTON,[33] and the arrangement included platform-sharing, with PROTON's first SUV to be developed from Geely's Boyue.[34] That is a rational commercial decision, and the cars sell. It is also, plainly, a case of acquiring technology rather than building it, in the very industry where Malaysia once set out to do the latter.
The lesson is not that Malaysia achieved nothing, but that building a domestic manufacturing industry and becoming a globally competitive technology producer are different accomplishments.
What about healthcare?
Malaysia has a substantial medical device manufacturing sector, producing everything from gloves and instruments to specialised components.[35] Yet much advanced hospital equipment — MRI and CT scanners, surgical robots and sophisticated laboratory analysers — is developed abroad.
Building research infrastructure is one achievement; turning Malaysian discoveries into widely used products is another. (I looked at the first of these in an earlier Kerbside Consult article, Medical Research in Malaysia: From Participant to Contributor, 40/2026, 5 October 2026.)
There is nothing wrong with purchasing the best equipment for patients, nor would it make sense to manufacture everything ourselves. But medical diagnostics, rehabilitation devices, digital health and selected biotechnology applications offer opportunities for original Malaysian innovation.
Our clinicians, scientists and engineers could work more closely together. Sometimes innovation begins not with a billion-ringgit programme, but with a clinician asking whether there is a better way to solve a problem. The difficult part is turning that idea into a safe, effective and commercially viable product.
Selected references: 35.
What should Malaysia aim for?
Malaysia does not need technological self-sufficiency in every field. Even advanced economies rely on international collaboration and global supply chains. Our aim should be to build stronger capabilities where we already have expertise and realistic opportunities to compete.
The examples in this article suggest three practical levers.
- Use big projects as anchors. The MRT shaped both a Malaysian innovation (the Variable Density TBM) and an export debut for Chinese machines. Large public projects can require co-development and local capability, not just delivery.
- Own the layer you can own. Gamuda's machines came from Germany, but the AI that drives them is its own. Where we cannot make the hardware, we can still own the software, design or IP.
- Measure outcomes, not just inputs. R&D as a share of GDP matters, but so do Malaysian-owned intellectual property, highly skilled jobs, exportable technologies and products that succeed internationally.
That also means sustained investment in education and research, closer university–industry collaboration, rewarding skilled people, and helping companies develop original technology. Foreign investment and new factories matter, but they are not the whole measure.
Back to the mountains
As I think back to our journey between Chongqing and Wulong, it is the tunnels I remember. Each was a hard engineering problem, solved. Together they made a difficult mountain road look easy. Above Wulong, Fairy Mountain rises to 2,033 metres,[36] and its forest park averages about 1,900 metres.[37]
But the deeper achievement was the knowledge, people, suppliers and long-term investment that made the tunnels possible.
Malaysia has the talent. Our work in tunnelling, precision engineering, medical gloves and semiconductors shows it. The challenge is not to start from nothing, but to build on what we have, and to create more opportunities for the next generation.
At the kerbside
Malaysia has real engineering achievements to point to: the SMART Tunnel, the Variable Density TBM, Gamuda's autonomous-TBM software, and precision-equipment makers selling to the world. Against that, R&D spending was 1.01% of GDP in 2022, against a national target of 2.5% by 2025, and the Auditor-General found the GERD objective unmet by June 2025. Industry's share of that spending is, encouragingly, rising.
Leads built on manufacturing know-how, as in gloves, can erode. Ownership of design, software and intellectual property lasts longer. Buying technology is not a failure; what matters is whether it becomes a step towards building our own.
A country's technological progress should not be measured only by the sophisticated equipment it can afford to buy, but also by the knowledge it develops and the technologies its people can create.
That, to me, is the real lesson from those tunnels through the mountains of China.